
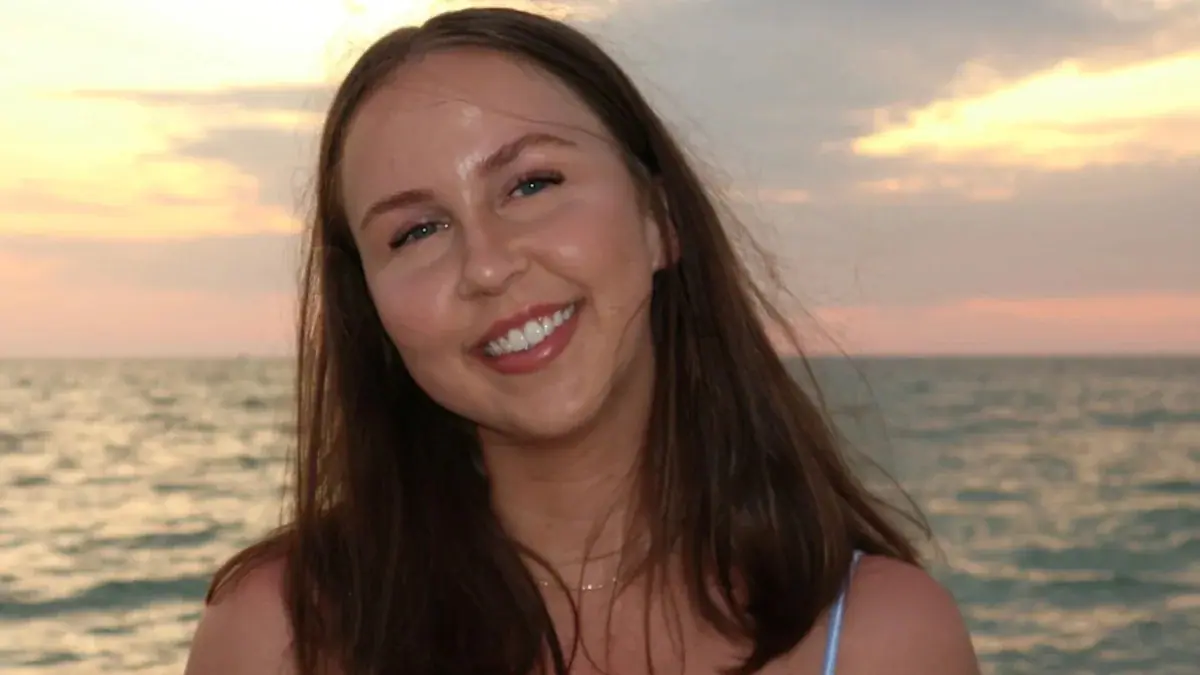
At age 24, when most people's careers and financial journeys are just starting, Erin Spencer decided she needed to start over.
A combination of student and car loans, credit liabilities, a bad breakup and "living outside my means" left her $65,000 in debt, as she said in People. So when a trusted colleague suggested she file for bankruptcy, she went for it.
"I couldn't afford the monthly payments toward my credit cards and line of credit, so when I filed, I was able to take a breath and almost start over," Spencer told Moneywise.
Must Read
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 moves to make before the window closes
Spencer added that she still had to pay her student and car loans, but that the bankruptcy significantly lowered the cost to $180 a month for nine months. "It felt like starting at rock bottom again, rather than a reset," she added, "but I don't regret doing it."
Now 31, Spencer is sharing her story on TikTok, demystifying bankruptcy and sharing advice to her younger self.
Spencer's advice — and a warning that hitting reset comes at a price
Personal bankruptcy generally falls under Chapter 7, which forgives some debt and liquidates assets to pay the rest, or Chapter 13, which involves a repayment plan to avoid liquidation.
Last year, the number of personal bankruptcy petitions filed in U.S. courts jumped 11% from 2024 to 533,337. The most common causes of bankruptcy in the U.S. remain job losses and medical debt, while student loans and credit debt are also high on the list.
Excluding mortgage debt, the average U.S. debt balance hit $21,603 in 2025.
John Cooper, a certified financial planner with Greenwood Capital, told Moneywise that bankruptcy "is a viable solution" for those struggling with high levels of debt, "but not without first considering [or] exploring other options" like debt counseling, debt consolidation or making efforts "to settle the debt for less than the full amount" with the creditor.
Those who do pursue bankruptcy may have to meet certain criteria and take debt counseling to be eligible. And bankruptcy negatively impacts your credit score for up to seven to 10 years, with Cooper warning that it could make it "difficult to secure a credit card, loan, et cetera, in the foreseeable future."
Story Continues