Key takeaways
The federal funds rate impacts how expensive it is for lenders to loan money, so consumer loan rates typically change when the federal funds rate changes.
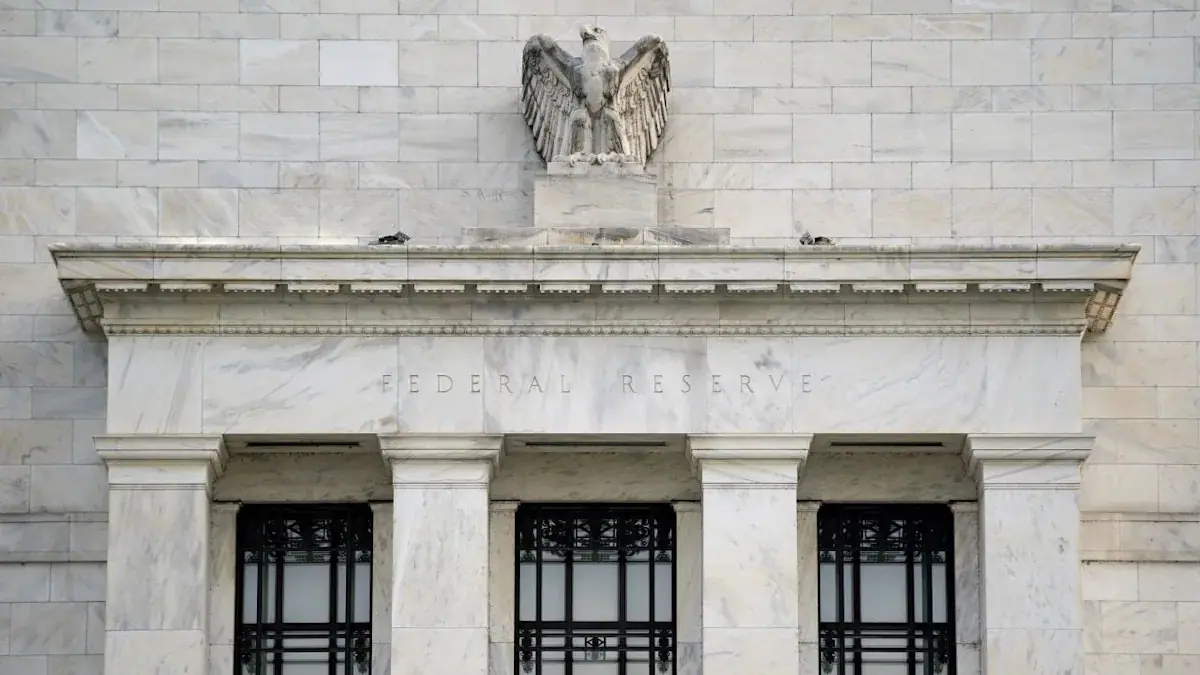
During the Federal Open Market Committee's September meeting, they chose to increase the target rate by a quarter of a percentage point.
Current personal loan rate trends suggest there won't be a major change personal loan interest rates in the near future, but the fed funds rate increase could cause some change in the market.
The fed funds benchmark rate impacts how much it costs for lenders to loan money, so it influences rates on consumer loans — including personal loans. The Federal Open Market Committee held the target rate steady between 3.75% and 4.00% in September 2026, following three quarter-percentage-point cuts and months of no movement. Because personal loan rates for new borrowers tend to follow Fed rate changes with a delay, they may continue slowly declining following this move.
The FOMC faces an unusual political and economic landscape as it makes rate decisions in 2026. Inflation lingers above the Fed's 2% target, discouraging further cuts. On the other hand, the Trump administration has signaled its upcoming nominee for Federal Reserve chair will push for cuts.
"The Fed is in a very good position to hold for a while and see how the economy actually evolves," Loretta Mester, an adjunct professor at the Wharton School of the University of Pennsylvania and former Cleveland Fed president, told Bankrate. "The labor market has stabilized, and they need to keep policy a bit restrictive to help inflation move back down to 2%. It's a good time to wait."
How does the Fed affect personal loans?
The federal funds rate influences the interest rates lenders offer to new borrowers because it impacts lenders' costs. When the rate is high, lending is more expensive. As the Fed introduced rate hikes throughout 2022 and 2023, the average personal loan rate also increased.
Even after three consecutive rate cuts in 2025, the industry average remains near historic highs. The FOMC's September decision to increase rates may budge the needle, but we won't know the market effects until lenders adjust their rates.
How the Fed impacts existing loans
The vast majority of personal loans are fixed-rate loans, meaning the interest rate remains unchanged from origination until it's paid off. Borrowers with a fixed-rate personal loan will not see changes to their interest rate or monthly payments when the Fed raises or lowers rates.
Story Continues