
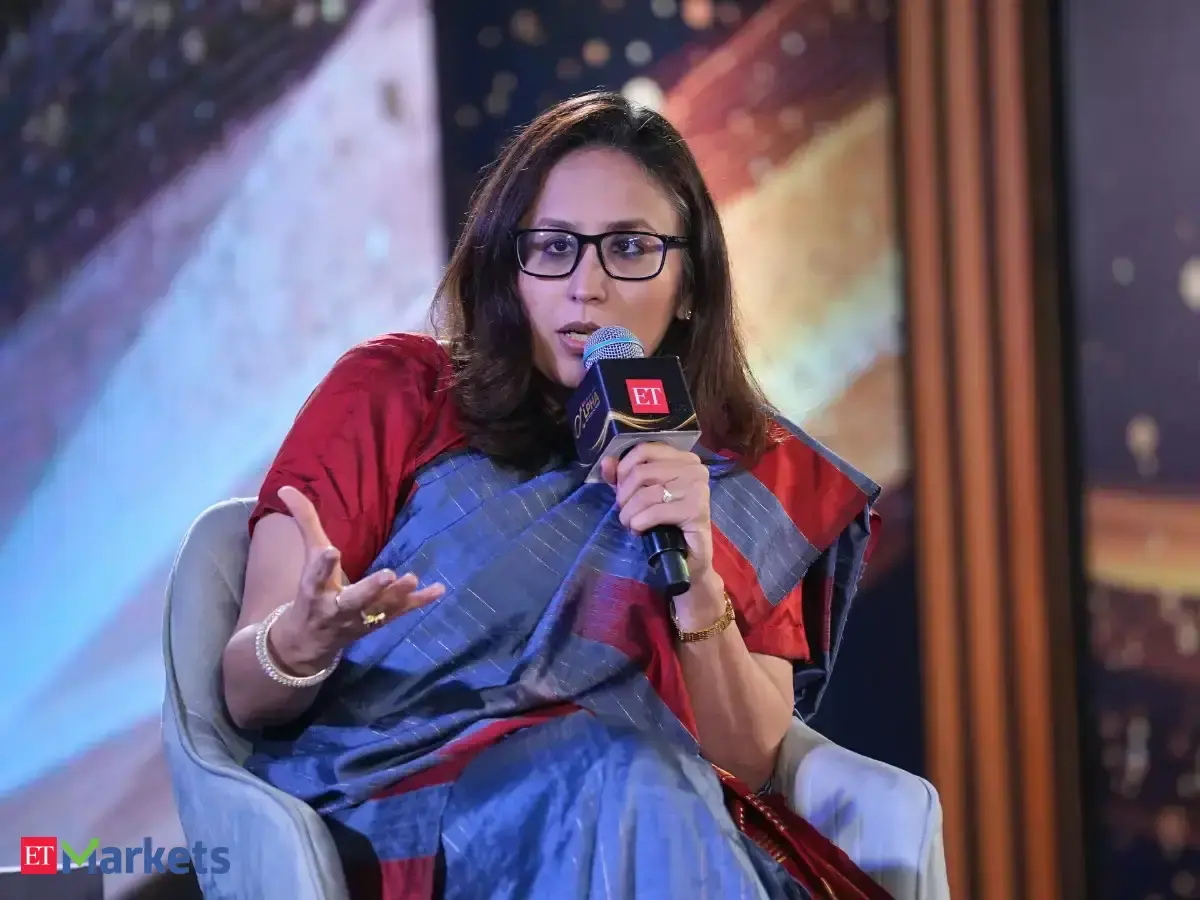
What would Specialised Investment Funds (SIFs) be if they were a Bollywood character? Radhika Gupta, MD and CEO of Edelweiss Mutual Fund, had a rather filmy answer at the ET Alpha Wealth Summit 2.0 in Mumbai. Her pick was Shah Rukh Khan, whom she described as versatile for his ability to switch between romance and action, adding with a laugh that “he does not come cheap.”
Behind the light-hearted exchange was a serious discussion on the evolving investment landscape and the growing role of SIFs in Indian portfolios.
“I love Shah Rukh Khan. See, Shah Rukh Khan, because he has done romance, he has done action, he is versatile and he does not come cheap,” Gupta said during the fireside chat.
The light-hearted exchange offered a memorable moment at a discussion that otherwise focused on a serious question facing India's wealth management industry: how should investors navigate an expanding universe of investment products, particularly Specialised Investment Funds (SIFs), without losing sight of their financial goals?
For Gupta, the answer lies in understanding what a product is designed to achieve, setting realistic expectations and ensuring that investors do not mistake product innovation for a reason to invest.
SIFs find their moment as markets turn challenging
Gupta said the first year of SIF launches in India had been encouraging, with the category's assets reaching around Rs 38,000 crore. Edelweiss Mutual Fund, she noted, had emerged as the largest SIF manager, with assets of approximately Rs 14,000 crore at the time of the discussion.
What stood out was not just the size of the industry but also the breadth and quality of investor interest. Gupta said the category was seeing around 500-600 transactions a day, with participation extending to investors in tier-II and tier-III cities.
She also pointed to the growing sophistication of conversations around strategies such as arbitrage and covered calls, suggesting that investors were increasingly engaging with the nuances of these products.
The timing of the launch, however, had presented a challenge. With equity markets under pressure, SIF managers had to demonstrate their strategies in a difficult environment rather than rely on a rising market to support returns.
Gupta compared the situation to a fast bowler performing on a difficult pitch, saying SIF managers had effectively been asked to deliver when market conditions were unfavourable.
In her view, this environment could also help investors understand the role these strategies are intended to play in a portfolio.
SIFs are not magic funds
A central message from Gupta was that investors should not expect a single financial product to deliver everything.
Investors may want a product that outperforms smallcap indices when markets rise and protects capital like a fixed deposit when markets fall. However, she argued that such expectations are unrealistic.
“You cannot have everything in one financial product,” she said, emphasising the importance of communicating a strategy's intended role, investment horizon and risks.
Using Edelweiss's hybrid long-short SIF as an example, Gupta said the fund had been positioned as an arbitrage-oriented strategy with an additional return component, rather than one designed to outperform aggressively in a bull market.
She also cautioned investors against treating such products as substitutes for liquid funds, noting that they could experience periods of negative returns.
For fund managers, the responsibility extends beyond showcasing returns. They must explain the conditions in which a strategy could underperform, the risks investors are taking and the period for which they should remain invested.
Gupta also highlighted the challenge of scaling strategies as assets grow. Techniques that may be easier to execute in a smaller fund can become more difficult as the fund expands, making consistent performance an important test for the industry.
Why taxation could tilt the balance towards SIFs
One of the strongest arguments Gupta made for SIFs concerned their tax treatment relative to other investment structures, particularly Category III alternative investment funds (AIFs) and portfolio management services (PMS).
Drawing on her experience of running a Category III AIF at Forefront Capital and managing a PMS, she explained how taxation can affect the returns investors ultimately receive.
Gupta illustrated the difference with a hypothetical calculation: to deliver an 8% post-tax return to an investor through a Category III AIF, a manager might need to generate a pre-fee return of around 16%, after accounting for taxes, fees and carry. Under the SIF structure, she estimated that generating an 11% return could deliver a comparable 8% in hand.
She argued that this difference could make the SIF structure more efficient for investors pursuing similar strategies, although actual outcomes would depend on performance, costs and the applicable tax treatment.
PMS structures face a different challenge, she added. Investors may incur capital gains tax when portfolio transactions are executed, whereas mutual fund structures generally defer investor-level capital gains taxation until redemption. Gupta said moving a concentrated midcap and smallcap strategy from a PMS structure into a mutual fund-based SIF could therefore improve tax efficiency.
Her broader message was that investors should look beyond the investment strategy alone and examine the structure through which it is offered.
Don't buy a SIF just because it is new
Despite her advocacy for SIFs, Gupta cautioned against treating them as must-have additions to every portfolio. She advocated “purposeful investing” or “shopping list investing”, urging investors to identify their needs before choosing products.
Adding new schemes simply because they are launched can make portfolios unnecessarily complicated. Instead, investors should assess their existing asset allocation and consider whether a SIF serves a specific purpose.
For instance, a hybrid SIF could suit a portion of a portfolio earmarked for returns over an appropriate investment horizon. Investors with existing midcap and smallcap exposure could also evaluate whether a SIF offers a suitable strategy for part of that allocation.
The choice, she emphasised, should depend on an investor's goals, risk appetite and portfolio needs, not a product's popularity. SIFs and mutual funds, she added, would continue to coexist as investors and advisers determine the right balance between them.
Understanding the strategy matters more than chasing returns
Gupta highlighted the need for investors and distributors to better understand derivatives, which give SIF managers greater flexibility in implementing strategies.
Derivatives can serve several purposes, including arbitrage, income-oriented strategies such as covered calls, and directional market positions. These approaches can carry very different risk and return profiles, despite falling under the broader SIF umbrella.
Gupta cautioned against comparing funds solely on performance rankings without understanding their underlying strategies. She also distinguished SIFs from leveraged retail derivatives trading, noting that SIFs are not permitted to use leverage.
Education and transparent communication will be essential as the category expands, she said. The industry must also deepen its derivatives expertise and demonstrate that strategies can deliver consistently as assets and investor participation grow.
For investors, the takeaway is simple: a new product is not automatically a better one. The right investment should address a specific portfolio need, offer an appropriate balance of risk and return, and fit the investor's time horizon.
Much like the Shah Rukh Khan analogy that opened the conversation, versatility may be attractive. But investors still need to understand what they are paying for — and whether their return expectations are realistic.
(Disclaimer: Recommendations, suggestions, views, and opinions given by experts are their own. These do not represent the views of The Economic Times.)
Add as a Reliable and Trusted News Source Add Now!
(You can now subscribe to our ETMarkets WhatsApp channel)
ET Alpha Wealth Summit 2.0: What do Shah Rukh Khan and SIFs have in common? Radhika Gupta explains
Edelweiss Mutual Fund MD and CEO Radhika Gupta says investors should approach Specialised Investment Funds (SIFs) with clear portfolio goals rather than chase new products or returns. Speaking at the ET Alpha Wealth Summit 2.0, she highlighted their tax efficiency, the importance of understanding derivatives-based strategies, and the need to assess risks, costs and realistic return expectations…
- Written by
- Kshitij Anand
- Published by
- The Economic Times
- Published
- Length
- 1,229 words · 6 min
Where this came from
This story was reported by Kshitij Anand and first published by The Economic Times on 11 October 2026. HUE Legacy Ventures did not write it.
Carried in full with attribution and a link to the original. Rights remain with the publisher, who may request removal at any time.