Our top picks of timely offers from our partners
More detailsLearn MoreTerms ApplyPaid PlacementBiz2CreditGet Prequalified up to $200,000 in business financing Learn MoreTerms ApplyPaid PlacementBig Think CapitalSmall Business financing that moves as fast as you doLearn MoreTerms ApplyMonarchOur top pick for being easy to use, Monarch's budgeting app is 50% off your first year of Core Plan with code CNBC50Learn MoreTerms ApplyBluevineBluevine offers fast funding options for your small businessLearn MoreTerms ApplySBG FundingFast and flexible financing options for your small businessSelect independently determines what we cover and recommend. We earn a commission from affiliate partners on many offers and links. This commission may impact how and where certain products appear on this site (including, for example, the order in which they appear). Read more about Select onCNBC, and clickhereto read our full advertiser disclosure.Money is simple. But when it comes to managing it, getting lost is also simple — and often painful.
It can be difficult to navigate the deluge of products and tools the financial services industry offers. What you need to achieve your goals is out there, but how are you supposed to identify it?
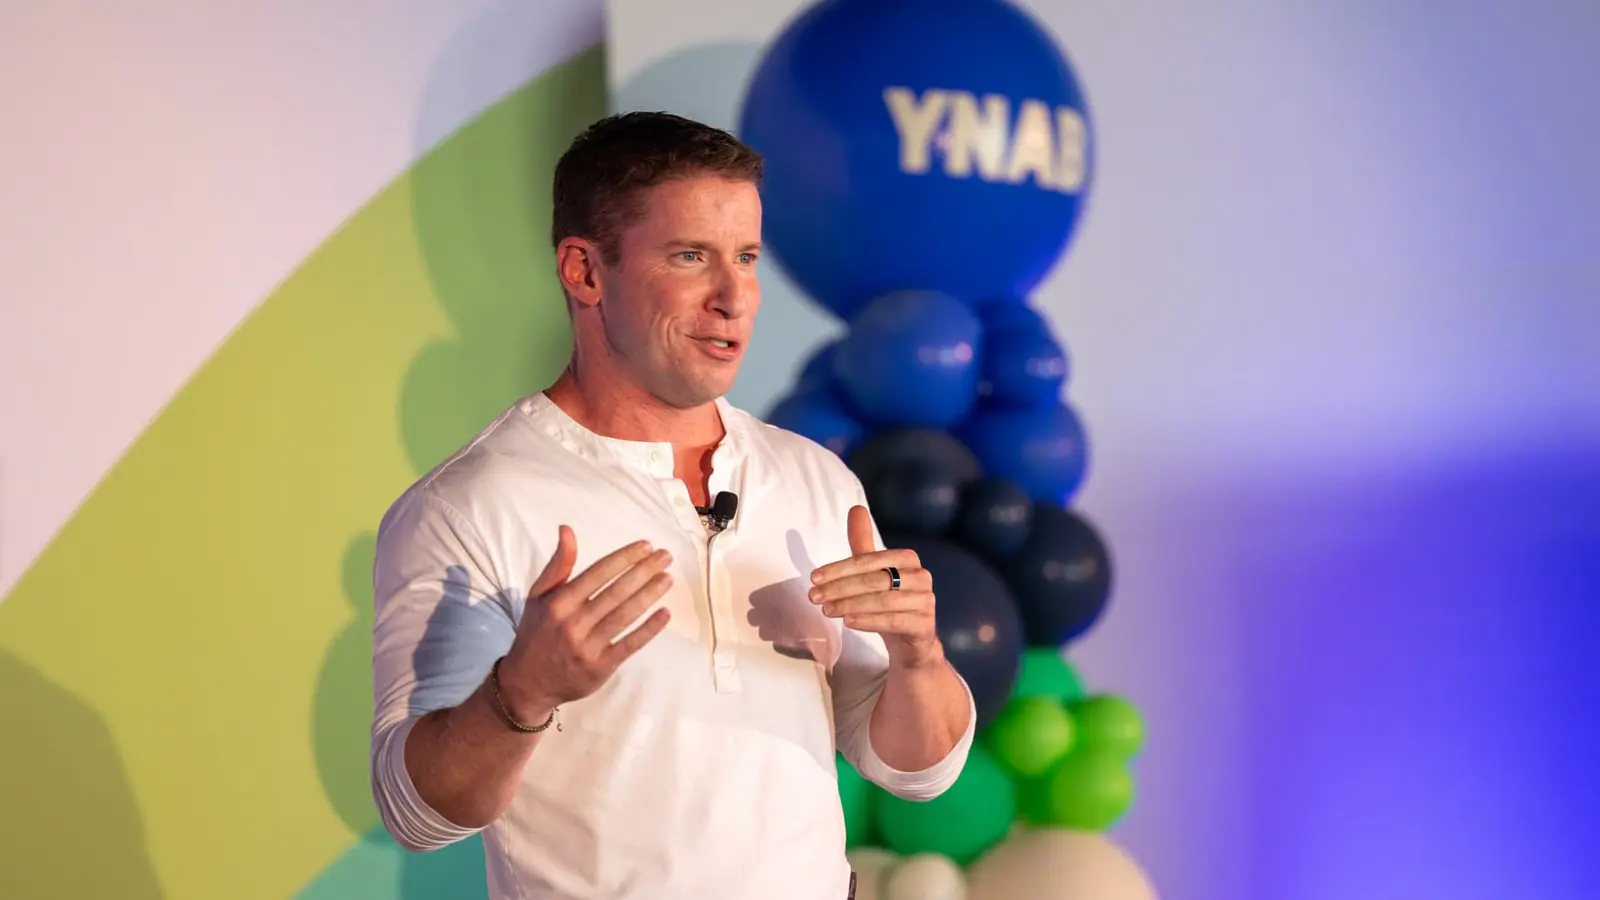
To help you find an answer, I asked the founder of the budgeting tool YNAB (previously known as You Need a Budget) and author of "Never Worry About Money Again," Jesse Mecham, to share his thoughts on how to identify the right financial tools for you. Here's what Mecham had to say.
How to find the right financial product for you
- Foster financial awareness
- Financial tools with signal
Senior reporter Jason Stauffer can answer your questions about how to make the most of your credit cards in his weekly Points Pro column. Submit yours here.
Foster financial awareness
Much of the stress around money is about timing, Mecham believes.
"In their minds, [people] say to themselves, 'I make good money. I make enough money. Why am I so stressed?' And so much of it is just a timing issue," Mecham tells CNBC Select.
Jesse MechamYNABWhen you get paid and when a bill is due don't always align. Financial products like credit cards and buy now, pay later services can exacerbate this timing mismatch by allowing you to spend money you don't have.
His solution to the lag between an expense and its payment is simple: Create a "signal."
"[A signal] is knowing what your money is doing. "But you must know what you're trading off." Signals or reminders of your current and future needs or wants help you make trade-offs that are better aligned with your goals.
To me, a good example of a tool that offers awareness and provides "a signal" is a mortgage escrow account. When your lender sets up an escrow account, it looks at your tax and insurance payments for the year and splits that cost into regular monthly payments, which are added to your mortgage payment. You may pay taxes or homeowners insurance only once or twice per year, which can create issues if you're not aware of when the bill is due and how much it will be.
An escrow account automates awareness and creates a signal through your monthly payment. It helps you understand what's going on with your money and the trade-off you're making by allowing you to pay for a future expense (in smaller chunks) now.
Financial tools that provide a signal
While Mecham admits this is a personal preference, he prefers to pay for services.
"I don't want to be a product. I don't want my data to be a product," he says.
When you pay for a product, you know the cost. If a free service makes money selling your data, it's more difficult to pinpoint the trade-off. You're paying for it, but not with money.
Below are a few tools that the staff at CNBC Select use to make sense of our money. In the spirit of Mecham's ideology, several of the services mentioned offer free tiers (albeit with fewer features than what you receive with a paid membership).
Budgeting apps
A budgeting app is a great way to increase your financial awareness. With the right money management tool, you won't need to guess how much you have left to spend, and you can reduce the impact of unexpected or irregular expenses.
I use and love the zero-based budgeting method where you assign money to categories as you earn it. Apps that use a zero-based philosophy include EveryDollar, Goodbudget and Actual Budget.
Goodbudget
Learn MoreCost
Free for 20 total envelopes; $10/month (or $80/year) for unlimited envelopes
Standout features
Allows users to plan their household's spending using the "envelope method," where they allocate a certain amount of their income into categories like groceries, rent and debt payoff. Users are only supposed spend what's in their envelopes and if they go beyond their budget the envelope will show red to indicate that they overspent
Categorizes your expenses
Yes, but users can customize
Links to accounts
No, users manually create "envelopes" and input their transactions
Availability
Has a web-based version, and also offered in both the App Store (for iOS) and on Google Play (for Android)
Security features
256-bit bank grade encryption in a data center
Terms apply.
Alerts on spending and bills
You can opt to receive notifications for many bills, such as credit card and utility payments. Most credit and debit cards allow you to set up spending alerts for transactions over a certain amount or when you hit a daily amount.
CNBC Select editor Claire Dickey uses Rocket Money, which offers budgeting and subscription tracking services so you can identify and cancel unwanted services. It can also send alerts when bills are coming due and lets you see your due dates in one place.
Rocket Money
Learn MoreCost
The basic plan is free. Rocket Money Premium is $7 to $14 a month with a 7-day free trial. Bill negotiation services cost 35% to 60% of the first-year savings, if the negotiation is successful.
Standout features
Easily cancel unwanted subscriptions, track your spending and credit score, automate savings and get help lowering bills. Rocket Money Premium includes additional services like net-worth tracking, credit reports and a subscription cancellation concierge service
Security
Rocket Money accesses transaction data via an encrypted token, uses Plaid API so user credentials are never stored, provides bank-level 256-bit encryption and hosts servers on Amazon Web Services
Availability
Offered online and on both the App Store (for iOS) and on Google Play (for Android)
Terms apply.
Pros
- Allows you to easily view and cancel unwanted subscriptions
- Offers a free version
- A+ from Better Business Bureau
Cons
- Nonrefundable bill negotiation fee can be up to 60% of savings
- Premium pricing varies
Automate investing or savings
Once you've decided what you want to use your money for, automating this decision is helpful. Setting up a direct deposit into your savings account or retirement account is a signal you don't have to think about and you can watch your accounts grow without lifting a finger.
The differences between banking and investing accounts typically aren't substantial, but pay attention to fees and interest rates. I use a Wealthfront Cash Account for most of my everyday banking. It has no monthly maintenance fees, an APY of at least 3.30% and I get up to two out-of-network ATM fee reimbursements each month (up to $7.50 back per transaction).
Wealthfront Cash Account
Learn MoreAnnual Percentage Yield (APY)
3.55% APY
Minimum balance
None
Monthly fee
None
Maximum transactions
Unlimited transfers and free same-day withdrawals
FDIC insurance coverage
Up to $8 million
Terms apply.
Pros
- Above-average APY
- No minimum balance or deposit
- No monthly fee
- Unlimited transfers and free same-day withdrawals
- FDIC insurance up to $8 million
Cons
- Limited customer support
The CNBC Select Recommends newsletter delivers practical money tips each week along with expert-picked financial product recommendations. Sign up here.
Why trust CNBC Select?
At CNBC Select, our mission is to provide our readers with high-quality service journalism and comprehensive consumer advice so they can make informed decisions with their money. Every article is based on rigorous reporting by our team of expert writers and editors. While CNBC Select earns a commission from affiliate partners on many offers and links, we create all our content without input from our commercial team or any outside third parties, and we pride ourselves on our journalistic standards and ethics.
Catch up on CNBC Select's in-depth coverage of credit cards, banking and money, and follow us on TikTok, Facebook, Instagram and X to stay up to date.